Audit & compliance
IAS 16 Property, Plant & Equipment: How Physical Asset Tagging Satisfies Kenya Auditors
IAS 16 asks you to carry assets you actually control at a value you can support. Physical tagging is how you prove the first half of that sentence.
IAS 16 governs how property, plant and equipment is recognised, measured and depreciated. Auditors testing that balance need evidence the assets exist, are in use and are recorded correctly. A tagged, verified register is the most direct evidence you can give them.
What IAS 16 asks of your fixed asset register
The standard requires assets to be recognised when it is probable that future benefits will flow to the entity and the cost can be measured reliably. It also requires depreciation over useful life and review of residual values and useful lives.
None of that works if the register lists items that are gone, damaged or never existed. The register is only as reliable as the physical link between each line and a real asset.
Why fixed assets attract audit findings
Common findings are familiar: assets in the ledger that cannot be located, assets in use that are not recorded, disposals never written off and missing location or custodian details.
Each one weakens confidence in the carrying amount of property, plant and equipment. Where the gaps are material, the auditor may qualify the opinion.
- Ghost assets: recorded but not physically present
- Unrecorded assets: present but missing from the register
- Unprocessed disposals and transfers
- No serial numbers, locations or custodians on file
How physical tagging closes the gap
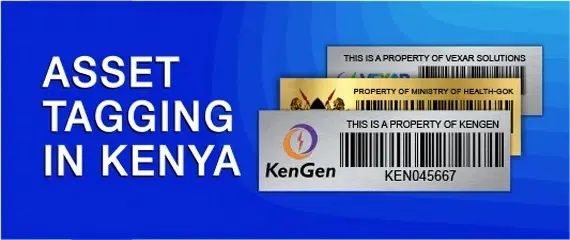
A unique tag number fixed to each asset becomes the key that joins the item to its register line. During a count, staff scan or read the tag instead of guessing from a description.
Recording the serial number, location, custodian and condition at the moment of tagging gives auditors a verifiable trail. Our fixed asset tagging services in Kenya follow this approach on every engagement.
Handling impairment, disposals and ghost assets
Verification often uncovers damaged or idle equipment. Condition notes captured during tagging give finance teams the evidence to consider impairment under IAS 36.
Missing items should be investigated, then written off with approval if they cannot be found. Leaving them on the register simply carries the problem into next year's audit.
An auditor-ready documentation checklist
Prepare the evidence before fieldwork starts. Auditors move faster, and ask fewer follow-up questions, when the pack is complete.
- Updated register with tag number, serial, location and custodian
- Discrepancy report: missing, unrecorded and damaged assets
- Signed verification sheets per location or branch
- Approvals for write-offs and transfers
- Tag number ranges issued, so sequences are traceable
Get your register audit-ready
Our team tags and verifies assets on site and hands over a reconciled register and discrepancy report.
Fixed asset verification servicesContinue reading
- How to Choose the Right Asset Tags for Your Business
Environment, asset value and how your team scans matter more than catalogue names. A step-by-step method for specifying tags you will not need to replace next year.
- Aluminium vs Barcode vs QR Code Asset Tags: Which Is Right for You?
These three options are often presented as competitors, but they answer different questions. Here is how material, code type and workflow interact.
- Why Every Business Needs an Asset Verification Audit
Registers drift quietly. A physical verification exercise turns an unreliable schedule back into evidence your auditors and board can rely on.
Ready to act on this?
Talk to our Nairobi team about tags, numbering or a verification exercise for your organisation.